The Wharton Global High School Investment Competition
Category: Blog
Which grade levels are eligible to participate in the WGHS Wharton competition? What topics are covered in the annual WGHS Wharton competition? What are the advancement and award rates for the WGHS Wharton competition? The "WGHS Wharton Updates" section is regularly updated to provide students with the latest information regarding the competition—specifically addressing the details they care about most.
Charts with different starting scales can create misleading visual comparisons. A larger numerical increase may still be a smaller percentage change. This fictional exercise is about reading quantities, not recommending an investment.
Index A rises from 50 to 60, a gain of 10 points or 20%. Index B rises from 200 to 220, a gain of 20 points or 10%.
B has the larger point increase, while A has the larger percentage increase. Neither description is wrong if its units and denominator are clear.
Normalise to a common starting level
Setting both initial values to 100 would put A at 120 and B at 110 at the end. This visualises the proportional changes without pretending their original values were equal.
Normalisation does not fix mismatched dates, different definitions or missing adjustments. Those need separate checks.
Ask what the measure includes
A price index, revenue series and total-return series can describe different things. Check the source, period and methodology before comparing slopes or endpoints.
This is general public financial literacy, not company analysis, a market forecast or a Wharton client recommendation. Competition participants should follow official rules and school-advisor support boundaries and produce their own work.
Wharton prohibits paid competition advisors, education consultants and non-Wharton courses claiming to teach the competition. Students must produce their own work. Use the official rules and your school advisor for questions about permitted support; the contact option here is for public information and resource links.
Contact Hanlin
Looking for official competition information or public learning resources? Scan the QR code and send WGHS CHARTS 1024. Include your school year, country or competition region, experience and the question you want to discuss.
Dividing cash by a monthly net outflow can produce a useful simplified estimate. It is not a guarantee about a real organisation's future. This fictional example focuses on reading the assumptions behind a number.
A fictional project has 6000 currency units of unrestricted cash. Assume monthly cash payments exceed receipts by a constant 800, with no new financing, exceptional payments or required minimum balance.
The simple cash-duration estimate is 6000/800 = 7.5 months. This uses net cash outflow, not revenue or accounting profit.
Test one changed condition
If net outflow rises to 1000 per month, the estimate becomes six months. If some cash is restricted to another purpose, it should not automatically be included in the available numerator.
Timing within a month also matters for actual payment ability. A fractional-month average model does not describe the date of every bill.
Keep the conclusion limited
The arithmetic depends on stable flows and the chosen definition of available cash. Real reports require source dates, definitions and evidence about variability.
This page offers public financial literacy, not advice about a company, security or Wharton client case. Competition participants should follow official rules and permitted school-advisor support, and produce their own work.
Wharton prohibits paid competition advisors, education consultants and non-Wharton courses claiming to teach the competition. Students must produce their own work. Use the official rules and your school advisor for questions about permitted support; the contact option here is for public information and resource links.
Contact Hanlin
Looking for official competition information or public learning resources? Scan the QR code and send WGHS CASH 1023. Include your school year, country or competition region, experience and the question you want to discuss.
An average can describe different populations. Averaging two listed prices is not the same as averaging the price paid across all items sold. Identify what receives one unit of weight.
A fictional shop sells 100 items at 10 currency units each and 10 items at 20 each. Revenue is 1000 + 200 = 1200 from 110 items.
The average price per item is 1200/110, approximately 10.91. The unweighted mean of 10 and 20 is 15, but it gives the two price categories equal weight rather than weighting each item equally.
Explain the weighted calculation
The weights are 100/110 and 10/110, which sum to one. Multiplying each price by its item share produces the same 10.91 result.
The answer lies closer to 10 because many more items were sold at that price. A result outside 10 to 20 would signal an error under these assumptions.
Read real averages carefully
Check the unit, population and period behind a reported average. Revenue weights, unit weights and equal category weights answer different questions.
This fictional calculation is general public learning material, not investment advice, client analysis or a competition submission. Wharton participants should follow official rules and their school advisor's permitted role and produce their own work.
Wharton prohibits paid competition advisors, education consultants and non-Wharton courses claiming to teach the competition. Students must produce their own work. Use the official rules and your school advisor for questions about permitted support; the contact option here is for public information and resource links.
Contact Hanlin
Looking for official competition information or public learning resources? Scan the QR code and send WGHS WEIGHTS 1022. Include your school year, country or competition region, experience and the question you want to discuss.
A percentage change always uses a base. After a quantity changes, the next percentage usually applies to a new base. This fictional arithmetic example offers general learning context, not a market forecast or portfolio recommendation.
A numerical index starts at 100 and falls by 20%, reaching 80. Increasing 80 by 20% gives 96, not 100, because the second increase is 16 rather than 20.
The combined growth factor is 0.8 × 1.2 = 0.96. Adding -20% and +20% ignores their different bases.
Calculate the recovery percentage
To move from 80 back to 100 requires an increase of 20 on a base of 80. The required percentage is 20/80 = 25%.
This is an arithmetic relationship. It does not tell us whether any actual asset, company measure or other quantity will recover, or how long a change would take.
Ask what the number represents
When reading a real chart, check its measure, units, starting date and whether adjustments have been made. A price change and a total-return measure may not be the same thing.
The example does not address a Wharton client case or supply student work. Competition participants should use official instructions and their school advisor for permitted support, while producing their own analysis and submissions.
Wharton prohibits paid competition advisors, education consultants and non-Wharton courses claiming to teach the competition. Students must produce their own work. Use the official rules and your school advisor for questions about permitted support; the contact option here is for public information and resource links.
Contact Hanlin
Looking for official competition information or public learning resources? Scan the QR code and send WGHS BASES 1021. Include your school year, country or competition region, experience and the question you want to discuss.
Some financial statements describe a period, while a balance sheet describes a date. Mixing a balance with a flow can produce an explanation that sounds quantitative but compares different kinds of information.
A fictional business has assets of 150 and liabilities of 90 at a stated date. Under the basic relationship assets = liabilities + equity, its equity is 60. All figures use the same currency units.
This arithmetic does not establish the market value of a company, nor does the asset total mean all assets are immediately available cash.
Follow one transaction
If the business borrows 20 and receives the cash, assets increase to 170 and liabilities to 110. Equity remains 60 in this simplified transaction.
A cash increase from borrowing is not automatically profit. The matching obligation matters, even though the bank balance has risen.
Match the time reference
Revenue for a year is a flow over that year. Cash at year end is a balance on a date. Ask which type a reported number represents before comparing it with another figure.
This fictional exercise provides public learning context, not investment advice or competition case analysis. Participants should use the official Wharton rules and their school advisor for questions about permitted support and produce their own work.
Wharton prohibits paid competition advisors, education consultants and non-Wharton courses claiming to teach the competition. Students must produce their own work. Use the official rules and your school advisor for questions about permitted support; the contact option here is for public information and resource links.
Contact Hanlin
Looking for official competition information or public learning resources? Scan the QR code and send WGHS SNAPSHOT 1020. Include your school year, country or competition region, experience and the question you want to discuss.
A larger amount of money does not necessarily buy proportionally more goods. This fictional general-literacy example compares a money amount with a price index. It offers no investment recommendation or competition portfolio analysis.
Suppose a money amount rises from 100 to 110 while a relevant price index rises from 100 to 108 over the same period. The nominal increase is 10%, while the index increases 8%.
To compare purchasing power using this index, divide the money growth factor by the price growth factor: 1.10/1.08 ≈ 1.01852.
Interpret the ratio carefully
The purchasing-power increase is approximately 1.85% in this simplified example. Subtracting 8% from 10% gives a nearby 2%, but it is an approximation rather than the exact ratio calculation.
The index represents a defined basket and methodology. It need not match every household's personal purchases, and the example does not identify a current inflation rate.
Read actual sources with their definitions
When a report says real growth, check which price adjustment, period and measure were used. Do not compare an annual money increase with a monthly index change without aligning the periods.
These calculations are public learning context only. Students participating in the Wharton competition should consult its official rules and their school advisor about permitted support. No client case, security selection or student submission is provided here.
Wharton prohibits paid competition advisors, education consultants and non-Wharton courses claiming to teach the competition. Students must produce their own work. Use the official rules and your school advisor for questions about permitted support; the contact option here is for public information and resource links.
Contact Hanlin
Looking for official competition information or public learning resources? Scan the QR code and send WGHS PRICES 1019. Include your school year, country or competition region, experience and the question you want to discuss.
A headline about rising revenue does not tell you whether profit rose. Different business measures answer different questions. This fictional numerical example is a public financial literacy exercise, not a company recommendation or competition investment strategy.
Suppose a fictional business reports revenue of 100 and profit of 10 in one period. In the next comparable period, revenue is 120 and profit is 9. Both periods use the same currency units and the same profit definition.
Revenue increased by 20 on a base of 100, so revenue growth is 20%. Profit fell by 1 on a base of 10, so profit growth is -10%. The two directions are different.
Calculate the margin
The first profit margin is 10/100 = 10%. The second is 9/120 = 7.5%. Margin has fallen by 2.5 percentage points.
Relative to the original 10% margin, that is a 25% decrease in the margin. A change in percentage points and a percentage change are different descriptions; write the denominator when calculating either.
Ask what could explain the difference
Costs may have risen faster than revenue, but these two headline figures do not identify the specific cause. Pricing, product mix, expenses and the definition of the reported profit measure could all require investigation.
Check that periods are comparable and that one measure has not been changed between reports. A number labelled adjusted profit may not have the same definition as another profit figure.
Use the figures to form questions
Good reading separates the calculation from its explanation. The calculation establishes what changed; additional evidence is needed to explain why it changed or what may happen next.
Record the source, date, units and definition for actual financial figures. This page supplies general learning context only. For the Wharton competition, students should follow the official rules and their school advisor's permitted role; this article does not supply a client analysis, security selection, portfolio recommendation or student submission.
Wharton prohibits paid competition advisors, education consultants and non-Wharton courses claiming to teach the competition. Students must produce their own work. Use the official rules and your school advisor for questions about permitted support; the contact option here is for public information and resource links.
Contact Hanlin
Looking for official competition information or public learning resources? Scan the QR code and send WGHS MARGIN 1018. Include your school year, country or competition region, experience and the question you want to discuss.
Two figures can rise together without one causing the other. Understanding that distinction helps students read business news more carefully. The following fictional example is a general evidence-reading exercise, not advice about a competition portfolio or client case.
A fictional shop spends more on advertising during a holiday month, and its orders also increase. The observation is that spending and orders rose during the same period.
The statement that advertising caused the increase is a stronger claim. Seasonal demand, a price change, new opening hours or several factors together could also explain the result. The observation alone does not isolate advertising's effect.
Look for a common cause
The holiday itself may influence both decisions: managers expect more shoppers and choose to advertise more, while customers buy gifts regardless of that particular advertisement. This creates a possible common cause.
It is also possible that stronger early sales encouraged more advertising later. Before discussing direction, ask when each decision and measurement occurred. A chart without a clear time sequence may hide this distinction.
Ask what comparison would be informative
A more useful investigation might compare similar periods or suitably comparable groups, while examining other differences. Randomised designs can help with causal questions when appropriate, but real studies still need careful implementation and interpretation.
Simply adding more observations does not automatically remove a systematic bias. Sample size, measurement quality and study design answer different questions.
Use wording that matches the evidence
With only the fictional monthly observation, write that higher advertising and higher orders occurred together. Then identify the additional evidence needed before making a causal claim.
When reading an actual source, record its date, definitions and limitations. This article offers public learning context only. Questions about permitted participation and support should be directed to the official competition rules and the school's advisor; no competition-specific research, investment selection or student submission is supplied here.
Wharton prohibits paid competition advisors, education consultants and non-Wharton courses claiming to teach the competition. Students must produce their own work. Use the official rules and your school advisor for questions about permitted support; the contact option here is for public information and resource links.
Contact Hanlin
Looking for official competition information or public learning resources? Scan the QR code and send WGHS EVIDENCE 1017. Include your school year, country or competition region, experience and the question you want to discuss.
A move from 12% to 15% can be described correctly in two ways, but the descriptions mean different things. Students exploring the Wharton Global High School Investment Competition benefit from defining the base of every comparison.
This is a fictional financial-literacy exercise, not an official client case, investment recommendation or competition strategy.
Suppose a fictional company's profit margin moves from 12% to 15%. Subtract the two rates: 15% - 12% = 3 percentage points.
Percentage points measure the distance between percentages. Calling this a 3% relative increase would be incorrect because it leaves the starting base unspecified.
Calculate the relative change
Relative to the initial 12% margin, the increase is (15 - 12)/12 = 25%. Thus a 3-percentage-point increase is a 25% relative increase in this particular rate.
These descriptions are compatible. They answer different questions: how far apart are the rates, and how large is the change compared with the starting rate?
Do not infer profit without revenue
If revenue stays at 1,000 currency units, profit moves from 120 to 150 units. But if revenue changes, the profit comparison needs that additional information.
For example, revenue of 800 units at a 15% margin gives profit of 120 units, equal to the original 1,000 x 12%. A higher margin does not by itself establish higher total profit.
Try a second comparison
A rate falls from 20% to 16%. The change is a fall of 4 percentage points. Relative to the starting 20%, the fall is 4/20 = 20%.
In general reading, write the original rate, new rate and denominator beside the calculation. Separate a numerical description from a forecast about future performance. Use Wharton's public information for the competition and keep registered-team work independent, following the current rules and school advisor's guidance.
Wharton prohibits paid competition advisors, education consultants and non-Wharton courses claiming to teach the competition. Students must produce their own work. Use the official rules and your school advisor for questions about permitted support; the contact option here is for public information and resource links.
Contact Hanlin
Looking for official competition information or public learning resources? Scan the QR code and send WHARTON PERCENT. Include your school year, country or competition region, experience and the question you want to discuss.
Interested in the Wharton Global High School Investment Competition, often called WGHS? Learning the language of financial statements is a useful starting point. Three numbers that can sound similar are revenue, profit and operating cash flow. They answer different questions, and a company can report three different amounts for the same period.
Wharton's official competition FAQ explains that the competition evaluates the strength and explanation of students' strategies and experiences, rather than percentage portfolio growth. Understanding what a financial number actually measures is a basic financial-literacy skill worth developing before drawing conclusions.
Exploring the competition or looking for public learning resources? Contact Hanlin with WHARTON FINANCIALS and tell us which information you are trying to find.
Revenue: How much was recognised from sales or services during the period?
Profit: What remains after the relevant expenses are deducted from revenue?
Operating cash flow: How much cash did operating activities bring in, net of the cash they used?
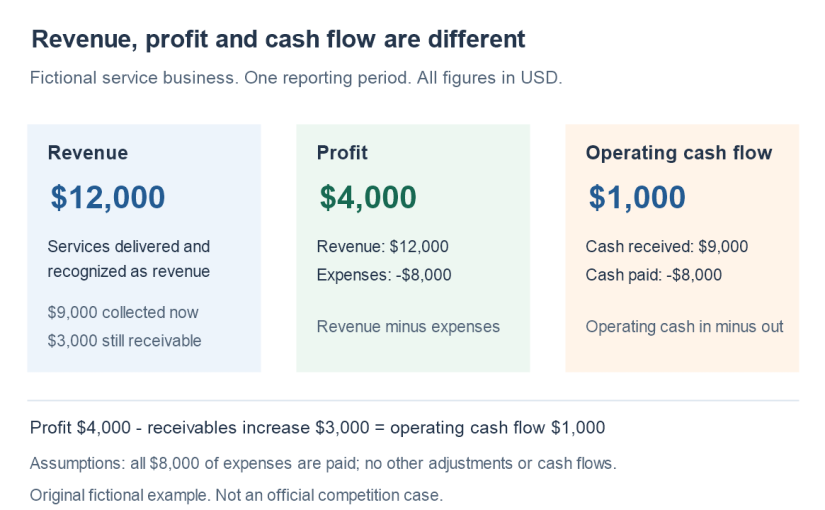
Revenue is not automatically cash received, and profit is not automatically cash generated. A short fictional example makes the distinction concrete.
A service business with $12,000 of revenue
Imagine a small service business during one reporting period. These are its only transactions:
It completes and bills $12,000 of services, all of which qualify for revenue recognition in this period.
Customers pay $9,000 before the period ends. The remaining $3,000 is still owed to the business.
It incurs $8,000 of operating expenses and pays all of them in cash during the same period.
Assume opening accounts receivable is zero and all other items, adjustments and cash flows are zero. These simplified figures are an original educational example, not a real company, an official competition case or an investment recommendation.
All figures are in USD. The example isolates customer payment timing so the three measures can be compared clearly.
Calculate profit and operating cash flow separately
For the income calculation, use the revenue earned and the expenses incurred:
Profit = $12,000 - $8,000 = $4,000.
For the cash calculation, use the money actually received and paid:
Operating cash flow = $9,000 - $8,000 = $1,000.
The business has earned $4,000 of profit, but only $1,000 of net operating cash has arrived during the period. Neither calculation contradicts the other: they measure different things.
Find the missing link: accounts receivable
The $3,000 that customers still owe is accounts receivable. In this example, it is already included in revenue but has not yet become cash.
Because opening receivables were zero, receivables increased by $3,000. Reconcile the two calculations:
This reconciliation works under the stated assumptions. A real company's reconciliation can contain other adjustments, so do not treat "profit minus receivables" as a complete general formula.
Cash flow is also different from the cash balance
The cash balance is an amount at a particular date; cash flow describes movement over a period. If this fictional business began with $5,000 of cash, its $1,000 increase would leave $6,000 at period end.
Real cash flow statements separate operating, investing and financing activities. The SEC guide explains these categories. Our example has no investing or financing activity, which is why its operating cash flow also equals its total cash increase.
Try two questions before opening the answers
In the next period, the business collects the remaining $3,000 from those customers. It provides no new services and has no new expenses or other transactions. How much additional revenue, profit and operating cash flow does that collection create?
Return to the original period, but suppose customers paid only $7,000 instead of $9,000. Keep the $12,000 of recognised revenue and $8,000 of cash expenses unchanged. What are profit, operating cash flow and ending receivables?
Show the answers and reasoning
Question 1: The collection creates $0 of additional revenue and $0 of additional profit. The revenue was recognised in the earlier period. Operating cash flow increases by $3,000, while receivables fall from $3,000 to zero. Counting the collection as new revenue would count the same services twice.
Question 2: Profit remains $12,000 - $8,000 = $4,000. Operating cash flow is $7,000 - $8,000 = -$1,000. Receivables are $12,000 - $7,000 = $5,000. The reconciliation is $4,000 - $5,000 = -$1,000. A positive profit and negative operating cash flow can therefore occur together in this simplified setting.
What this exercise establishes, and what it leaves open
The calculations establish that payment timing can separate revenue, profit and cash flow. They do not establish whether the fictional customers will pay on time, whether future sales will grow or what an ownership share would be worth.
Keep those questions separate from the arithmetic. "Customers still owe $3,000" is a stated fact in the example. "They will pay next month" would be an additional assumption unless the exercise supplies it.
For independent study, keep a note of the metric, reporting period, units and source beside each figure. Use Wharton Global Youth's public glossary to look up unfamiliar business terms, then explain them in your own words.
Use the official competition information alongside public learning
If you are exploring WGHS, begin with the official overview and our beginner's guide. Registered teams should follow the current instructions supplied by Wharton.
Wharton's General Rules & Roles prohibit paid advisors, education consultants and non-Wharton extracurricular courses claiming to teach the competition. Students are responsible for their research, decisions and submitted work. Ask Wharton and your school advisor about permitted assistance.
Explore the Wharton competition with Hanlin
Want to understand the event or find public financial-literacy resources? Scan the QR code and send WHARTON FINANCIALS. Tell us which official information or public learning links you are looking for.
On your phone, use the button above. You can also save the QR image and scan it within WeChat.
Include these details in your message: WHARTON FINANCIALS School grade: Country or region: Status: exploring a future season or already registered. Information needed: event overview, official rules or public learning resources.
Sources: Wharton Global Youth's competition overview, FAQ, rules and glossary, and the SEC's beginner guide linked above. The fictional example, diagram and exercises were created for this article.
💬Online Customer Service
Hello, classmate. I am Institute Teacher, providing you with:
🎯International Competition Planning
🚀Study Abroad Profile Enhancement
📚International Curriculum Exam Preparation
🏫International School Selection
🎁 Get free resources now
Competition Registration / Benefit Collection
Please click the button below to claim directly↓↓↓